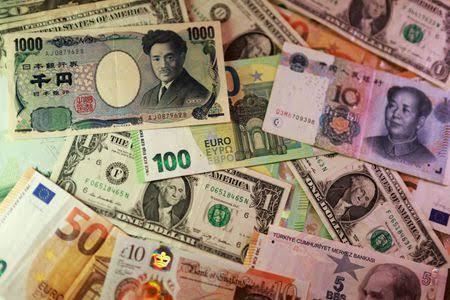
Governments around the world are increasingly exploring bond markets outside the United States dollar as rising borrowing costs and competition for investor funds make public financing more challenging. The shift is drawing attention to currencies such as the Chinese yuan, Australian dollar, Hong Kong dollar and Singapore dollar, as sovereign borrowers look for additional ways to finance infrastructure, energy projects, defence spending and economic development.
The development comes at a time when governments and private companies are competing for capital in an increasingly demanding financial environment. Public authorities need funding for essential services and long-term investment, while businesses are raising money to expand operations, refinance debt and finance technology projects. The rapid growth of artificial intelligence infrastructure has added another source of demand for financing.
According to Reuters reporting on October 15, 2026, Citi’s global head of public sector group, Stephanie von Friedeburg, said governments and state-linked entities were showing greater interest in issuing bonds in currencies other than the US dollar. She pointed to competition between public-sector borrowers and private companies for a limited pool of available capital.
The shift does not mean that the dollar is about to lose its dominant position in international finance. The US currency remains central to global trade, foreign-exchange reserves and international debt markets. However, the search for alternative funding channels highlights the growing importance of diversification as borrowers respond to higher financing costs.
For investors, the trend creates new considerations involving currency exposure, interest rates, sovereign credit quality and the relative attractiveness of different bond markets. For governments, issuing debt in another currency can broaden the investor base, but it also introduces risks that must be managed carefully.
The central question is whether non-dollar bond issuance will become a lasting part of sovereign financing strategies or remain a selective option used when market conditions make it attractive.
Why Governments Are Looking Beyond the US Dollar
The US dollar has long dominated international bond markets because of the depth of the Treasury market, the currency’s extensive use in global trade and the broad participation of banks, asset managers, pension funds and central banks.
Dollar-denominated bonds give governments access to a large international investor base. However, that access does not guarantee low borrowing costs. When US Treasury yields rise, the cost of financing in dollars can increase for sovereign issuers around the world, even when their domestic economic conditions differ from those in the United States.
Higher yields can create particular difficulties for developing economies that need to refinance existing obligations while funding public infrastructure and essential services. A government facing substantial interest payments may have less room in its budget for transport, electricity, healthcare and education.
Borrowing in other currencies can provide another route to investors. A government might issue bonds in a currency that is widely used by investors in its region or one that matches the funding needs of a particular project.
For example, an Asian government financing a regional infrastructure project could assess whether a bond denominated in an Asian currency would attract investors whose portfolios and financial obligations are already concentrated in that market.
The decision depends on several factors, including investor demand, the issuer’s credit standing, market liquidity, transaction costs and the expected cost of servicing the debt over its lifetime.
Currency choice also affects risk. If a government earns most of its revenue in its domestic currency but borrows in a foreign currency, depreciation can make repayment more expensive. Issuing debt in a different international currency does not automatically eliminate that problem.
As a result, governments must compare the full financing cost with the risks associated with each currency rather than simply choosing the market offering the lowest initial interest rate.
Rising Bond Yields Increase Pressure on Public Finances
Government bond yields have become an important concern for financial markets during 2026. Yields determine how much governments must offer investors to borrow through newly issued securities and influence financing costs across the wider economy.
Reuters reported on October 15 that benchmark 10-year yields in the world’s 10 largest developed economies had risen by an average of 81 basis points during the year, according to remarks by Citi’s public-sector financing leadership.
A basis point represents one-hundredth of a percentage point. An 81-basis-point increase is therefore equivalent to 0.81 percentage points.
The consequences depend on how much debt a government needs to issue, when existing bonds mature and whether its borrowing costs are fixed or variable. Governments with substantial near-term refinancing requirements may feel the effects sooner than those whose debt has longer maturities.
A rise in market yields does not immediately increase interest payments on every outstanding fixed-rate bond. Existing securities generally continue paying their agreed coupons until maturity. However, when governments refinance maturing debt or raise additional funds, they may need to accept the new market rate.
Over time, higher refinancing costs can place additional pressure on national budgets. Governments may need to reconsider spending priorities, adjust borrowing plans, increase revenue or seek ways to improve the efficiency of public investment.
The effects can extend beyond sovereign issuers. Government bonds help establish reference rates for mortgages, corporate debt and other financial products. When yields rise, businesses may face higher financing costs, while households can encounter more expensive borrowing.
These links explain why changes in government bond markets receive close attention from investors and policymakers. The cost of sovereign financing can influence investment decisions throughout the economy.
Artificial Intelligence Is Adding to Competition for Capital
The expansion of artificial intelligence infrastructure has become another factor influencing global capital allocation. Technology companies are investing heavily in data centres, computing equipment, electricity supply, networking and related infrastructure to support demand for AI services.
Some of these investments are financed through corporate cash flows and equity capital. Others rely on loans, bonds and private financing arrangements. The resulting demand for funding can place technology companies in competition with governments and other businesses seeking investment capital.
The timing of these financing needs matters. Infrastructure projects often require substantial spending before they begin generating their expected returns. Investors must assess whether future revenue will justify the initial expenditure, particularly when borrowing costs are high.
If financial markets become less confident about the expected returns from AI investments, some companies may face greater scrutiny when seeking new debt. Investors could demand higher yields or stronger contractual protections before providing funding.
That does not mean AI investment will necessarily decline across the board. Companies with strong cash generation, credible business models and clear customer demand may continue to attract financing. The pressure is likely to vary according to each borrower’s financial position and the expected profitability of its projects.
Governments also face their own capital requirements, including investment in energy systems, transport, defence and digital infrastructure. They cannot assume that private investment will always be available on affordable terms.
This competition helps explain why public-sector borrowers are considering a wider range of bond markets. Diversification can expand financing options, although it cannot remove the underlying competition for savings and investment funds.
The Role of Asian Currency Bond Markets
Asian currency markets are attracting interest from issuers looking to diversify their financing. The Chinese yuan, Australian dollar, Hong Kong dollar and Singapore dollar each operate within different financial and monetary arrangements, giving borrowers several potential options.
The yuan has become more important in cross-border trade and financing, particularly for transactions involving China. Governments and companies with economic ties to Chinese markets may consider yuan-denominated debt where investor demand and repayment arrangements make it suitable.
However, yuan financing involves specific considerations. China’s financial system operates under its own capital-management rules and monetary policy arrangements. International investors must evaluate access to the market, the terms of the bond and the ability to convert or transfer funds under applicable regulations.
The Australian dollar provides access to an established bond market supported by domestic institutional investors and international participation. Issuers considering Australian-dollar debt must evaluate Australian interest rates, currency movements and demand for their particular credit profile.
Hong Kong’s financial markets serve international investors and regional businesses, while the Singapore dollar is important within Southeast Asian finance. Both markets can offer access to investors with regional expertise, but issuance conditions vary according to market liquidity, deal size and the issuer’s credit quality.
For governments, selecting a currency requires more than identifying a market with active investors. The currency should fit the government’s broader debt-management strategy, including its revenue sources, foreign-exchange reserves and expected future payments.
A government that borrows in a foreign currency without a reliable way to manage exchange-rate risk may find that currency movements eventually outweigh any initial savings on interest.
Non-Dollar Issuance Does Not Mean the Dollar Is Losing Its Dominance
The growing interest in alternative currencies should be viewed as diversification rather than proof of an imminent collapse in dollar demand.
The US dollar benefits from deep and liquid financial markets, extensive international use and the central role of US Treasury securities in global investment portfolios. These characteristics make it difficult for another currency to replace the dollar across all major financial activities.
International investors often use Treasury securities as reference assets when evaluating the prices and risks of other bonds. The dollar also remains widely used in trade finance, foreign-exchange transactions and the management of international reserves.
Other currencies can still gain importance in specific areas without displacing the dollar overall. A government might issue a bond in an Asian currency to attract regional investors while continuing to use dollar markets for other borrowing needs.
This approach can help issuers broaden their investor base and reduce dependence on a single funding channel. It may also allow governments to match particular financing requirements with investors who have a natural interest in the relevant currency or region.
However, issuing bonds across several currencies can make debt management more complex. Governments must track different interest-rate environments, maturity schedules, market conventions and exchange-rate exposures.
The most appropriate strategy will depend on the issuer’s financial position and long-term objectives. A diversified funding plan can improve flexibility, but diversification alone does not guarantee lower costs or reduced risk.
What Investors Should Examine in Sovereign Bonds
Investors evaluating government bonds need to consider several factors beyond the advertised yield.
The first is credit risk. A government’s ability to meet its obligations depends on its revenue base, debt burden, economic prospects, institutional capacity and willingness to service its debt.
The second is interest-rate risk. Bond prices generally move in the opposite direction to market yields. When yields rise, the prices of existing fixed-rate bonds typically fall, with longer-maturity securities often showing greater sensitivity to changes in rates.
Currency risk is another central consideration for investors buying bonds denominated in a currency different from their own. Even if a bond pays interest as scheduled, exchange-rate movements can reduce the investor’s return when proceeds are converted back into the investor’s home currency.
Liquidity also matters. A bond market with limited trading activity can make it more difficult to buy or sell securities without affecting the price. Smaller or less frequently traded issues may therefore require additional compensation to attract investors.
Investors must also assess inflation and monetary policy. Inflation can erode the purchasing power of future coupon payments, while central bank decisions can influence yields and exchange rates.
Finally, the purpose of the borrowing deserves attention. Financing productive infrastructure with a credible economic return is different from borrowing to cover recurring expenditure without a sustainable revenue plan. The distinction is not always straightforward, but it can help investors understand the risks behind a bond issue.
Implications for Developing Economies
Developing economies may have a particular interest in expanding their financing options because they often need substantial investment in infrastructure, electricity, transport, water systems and public services.
Access to additional currency markets could help governments reach investors beyond their traditional funding sources. It may also provide an opportunity to develop domestic bond markets and encourage longer-term institutional investment.
Nevertheless, international borrowing carries risks that can be especially difficult for countries with limited foreign-exchange reserves or concentrated export earnings.
A country that relies heavily on commodity exports, for example, may experience pressure on its finances when global prices fall. If it also owes substantial amounts in foreign currencies, weaker export revenue can make debt service more difficult.
Currency mismatches can create similar problems. When public revenue is collected mainly in local currency but debt payments are denominated abroad, a depreciation can increase the domestic-currency cost of repayment.
Developing countries therefore need coherent debt-management strategies, reliable fiscal data and careful evaluation of the projects financed through borrowing. Choosing a different bond market is only one part of that process.
Multilateral development banks, domestic pension funds and regional investment institutions can also contribute to financing plans. In some circumstances, guarantees or other risk-sharing arrangements may help attract private capital, although they do not eliminate the need to assess the underlying debt burden.
What Comes Next for Global Bond Markets
The outlook for sovereign bond issuance will depend on borrowing costs, investor demand, central bank policy and the pace at which governments need to raise new funds.
If yields remain elevated, public-sector issuers may continue exploring different currencies and investor groups. Some governments could seek to diversify their funding schedules, while others may focus on extending maturities or improving the structure of their existing debt.
Demand for non-dollar bonds will also depend on the investment opportunities available in each market. Investors compare yields with expected inflation, currency risk, liquidity and the credit quality of the issuer. A new bond will need to offer an attractive balance of return and risk to secure strong demand.
The AI investment cycle could remain an important influence. If technology companies continue to raise substantial amounts of debt, competition for capital may persist. If investment plans slow or financing requirements decline, pressure on available funds could ease, although government borrowing needs would remain.
For investors, the development highlights the importance of looking beyond headline yields and currency labels. The quality of the borrower, the structure of the bond and the risks associated with repayment are central to evaluating an investment.
For governments, access to more bond markets can provide flexibility, but sustainable public finances remain essential. Borrowing in a different currency cannot compensate for weak fiscal management or an inability to generate the resources needed to meet future obligations.
The increasing interest in non-dollar bonds is therefore best understood as a response to a more competitive global financing environment. It reflects governments’ efforts to broaden their options while public and private borrowers seek funding for a wide range of priorities.
The dollar remains central to international capital markets, but the growing use of alternative currencies could gradually reshape how individual governments raise money. Whether that trend becomes more significant will depend on the cost of financing, investor appetite and the ability of issuers to manage the risks that accompany international borrowing.